Key Developments
Our top market developments of the past month are as follows:
1) Higher Everything? – Economic growth, interest rates, and oil prices all surged in September. Payrolls rose 162K (consensus ~55K), core retail sales jumped 1.4%, and flash PMIs hit their highest since 2021 – even as 10-year yields leapt 55bp to 5.30% and crude held above $100. Growth is powering through costlier energy AND costlier money.
2) Bigger was Better – The S&P 500’s modest 0.45% dip masked an equal-weight index down 5.2% and the Russell 2000’s worst month since early 2025. Smaller companies are sensitive to rising rates, while mega-caps are both protagonists and beneficiaries of the AI capex boom. META rose 26.7%, with tech and communications the only positive sectors.
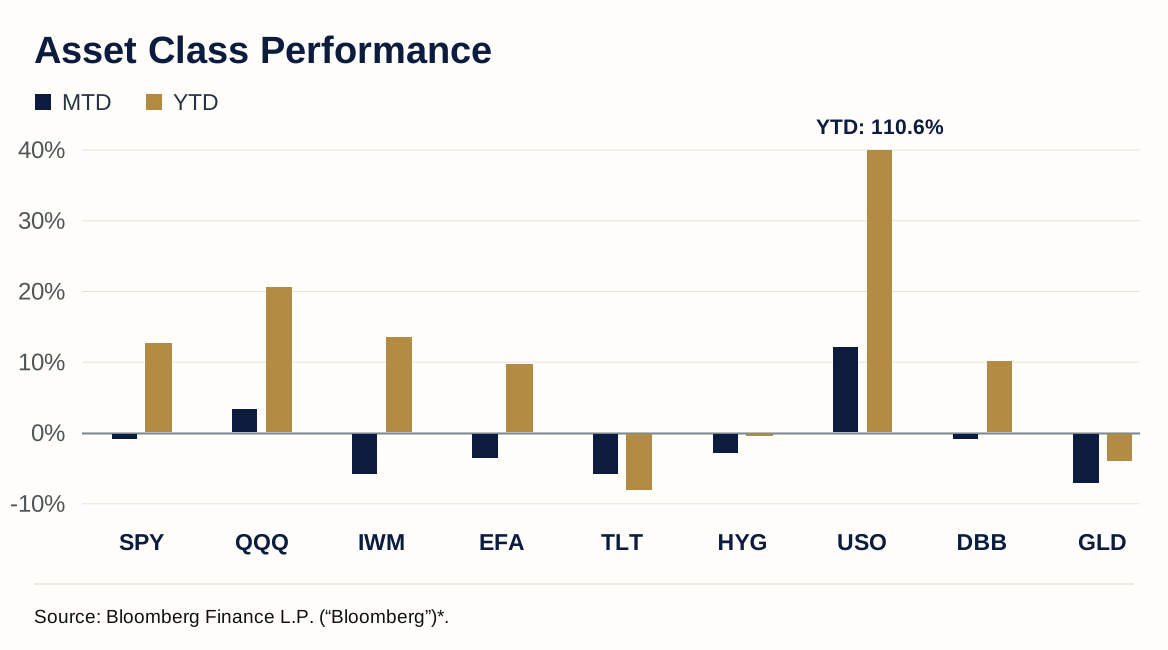
3) Strait Flush – Oil keeps escaping the Strait of Hormuz in quantities far greater than had been thought possible (by some metrics approaching pre-war levels) via “dark crossings” through the US-protected Omani Corridor. With crude still above $100, markets must be questioning how durable these flows could truly be.
* Through Sep. 30, 2026; SPY (SPDR S&P 500 ETF Trust); QQQ (Invesco QQQ Trust Series 1); IWM (iShares Russell 2000 ETF); EFA (iShares MSCI EAFE ETF); TLT (iShares 20+ Year Treasury Bond ETF); HYG (iShares iBoxx High Yield Corporate Bond ETF); USO (United States Oil Fund LP); DBB (Invesco DB Base Metals Fund); and GLD (SPDR Gold Shares).
Portfolio Considerations
➢ What, me worry? – A surge in demand for capital has flipped the world from the Bernanke-era “savings glut” into capital scarcity. To fund the AI-driven buildout of computing power, other uses of capital must get priced out. AI investment paybacks can be as short as two years, in which case it hardly matters whether money costs 8% or 12%. Purchases of homes, autos, and durables must go to the back of the line, as only the strongest uses of capital will survive.
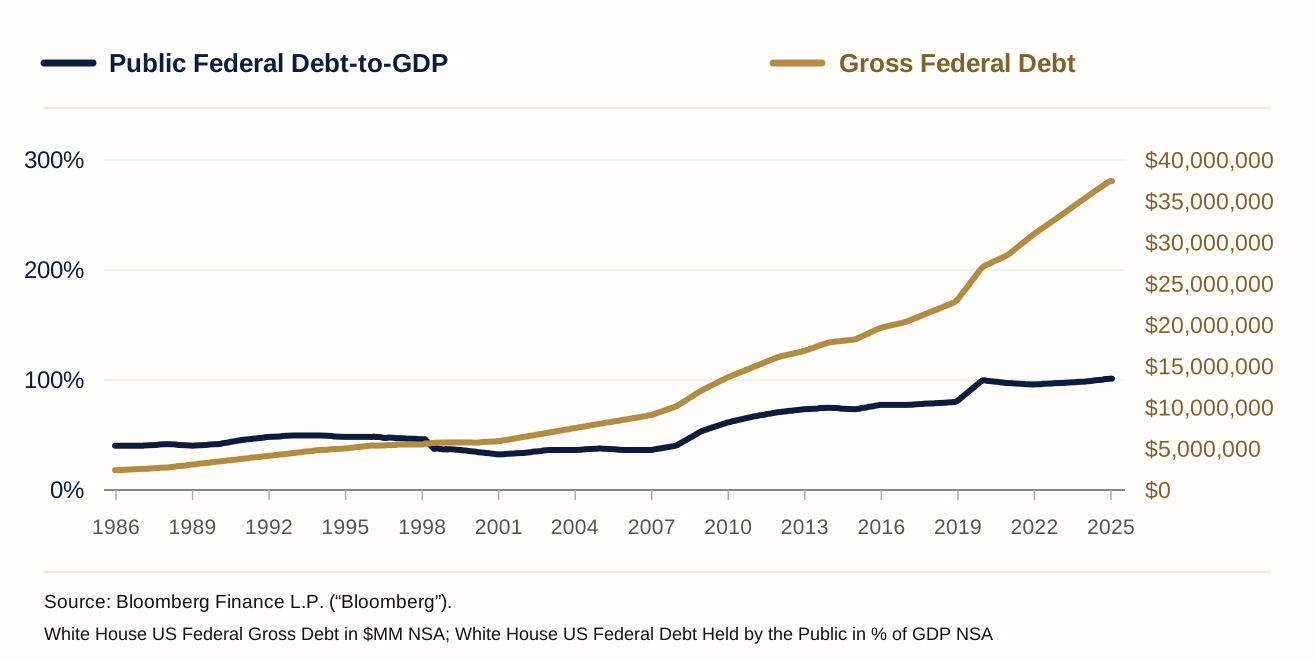
Deficit concerns, meanwhile, may be overblown as a driver of current rate moves. While overall debt continues to rise, with nominal GDP growing at 6 to 7%, debt can grow at a similar pace and debt-to-GDP stays constant. If growth accelerates once we clear the “J-curve” of AI investment, debt ratios could even come decline.
Looking forward…
➢ One and Done? – Markets’ knee-jerk pricing of multiple further hikes could prove excessive. Energy prices are driving almost everything of late – so should oil continue to flow and prices moderate, we may find that Warsh’s recent credibility-protecting rate hike may be all that is needed.
Disclosure
Investors should consider the investment objectives, horizons, income tax brackets, risks, charges and expenses of any variable product carefully before investing. This and other information about the investment company is contained in each fund’s offering memorandum, which can be obtained by emailing info@gideonsp.com. Please read it carefully before you invest.
By accepting these materials, the recipient agrees to keep the materials and their content confidential and not to use them or the content for any purpose other than to evaluate a financial transaction with Gideon Strategic Partners, LLC of the type described in the materials, except that there is no limitation on the disclosure of the tax treatment or tax structure of the products and transaction structures contained herein. Any unauthorized use or disclosure of these materials without Gideon Strategic Partners, LLC’s written consent is prohibited.
Securities and Investment Advisory Services offered through Simplicity Investments. Securities Dealer, Member FINRA/SIPC; TLG Advisors, Inc. Registered Investment Advisor; 475 Springfield Ave., Summit, NJ 07901 (303) 797-9080. Gideon Strategic Partners is not affiliated with Simplicity Investments.